For financial advisers, planners and wealth managers
The space between the plan and what it's meant to achieve.
Your numbers are right, and your client still won't spend. Or they're spending too much and need to readjust. Perhaps they can't say what retirement or their financial legacy is to them. Whether you are a wealth manager, a planner or an adviser, I work in the psychological space that you cannot, and never give financial advice.
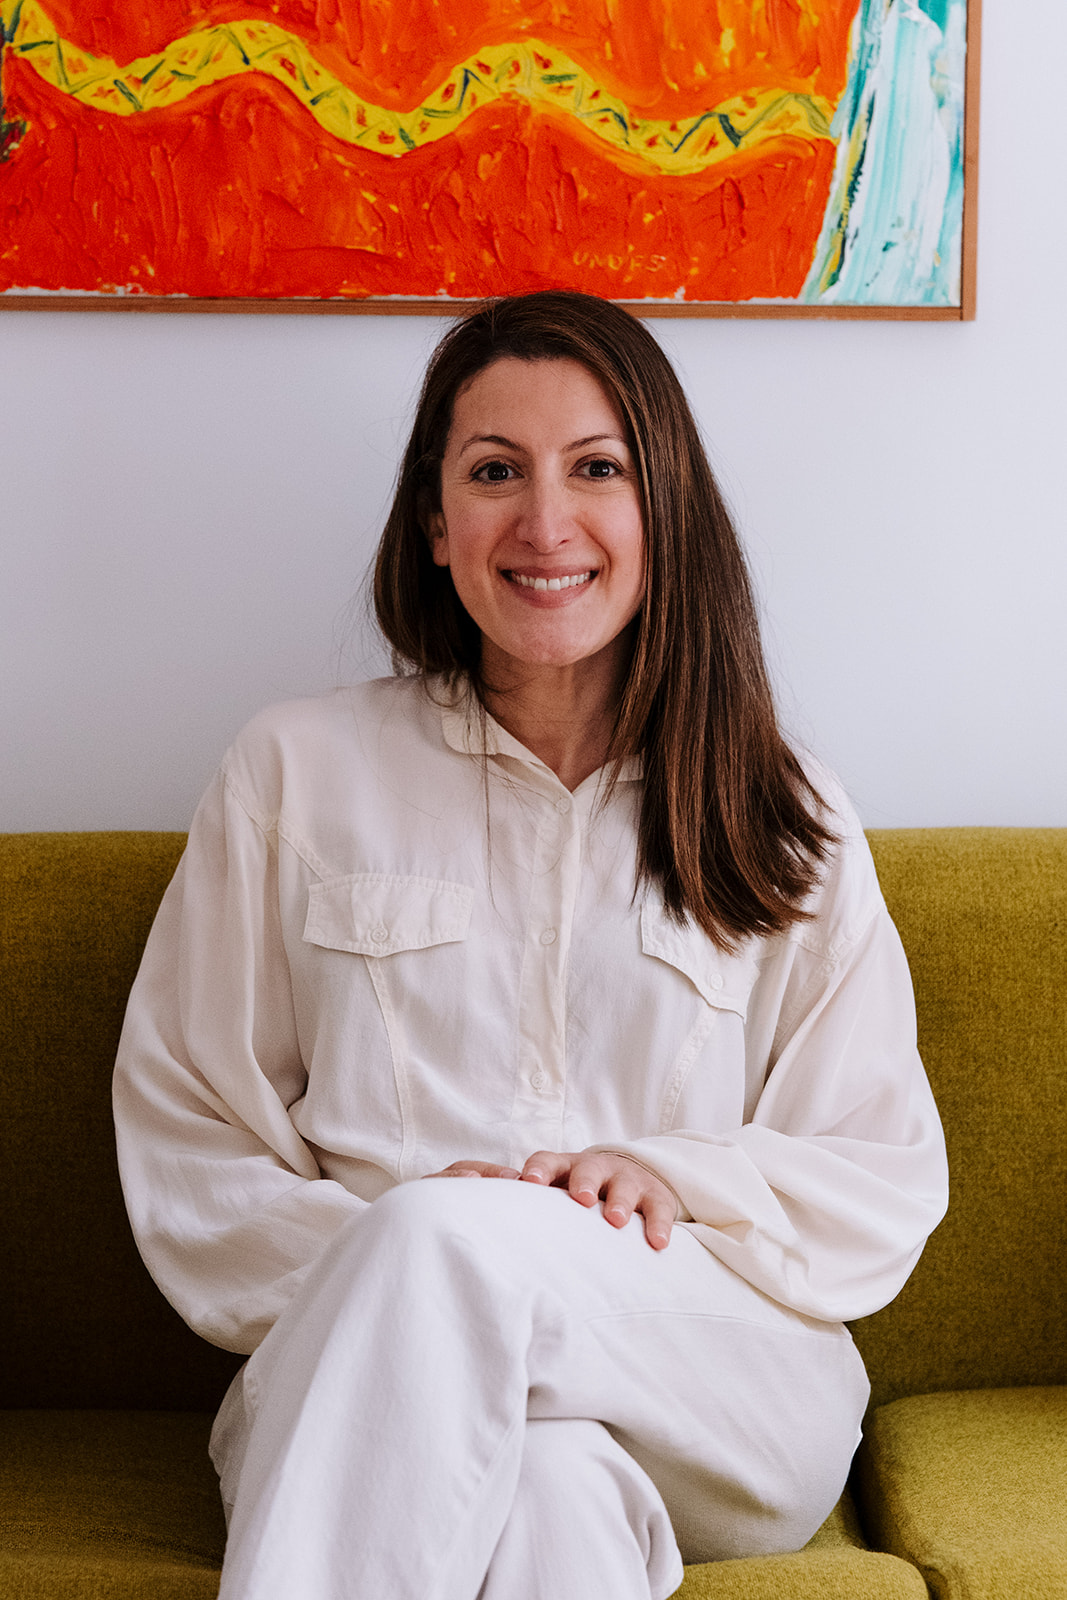
Sarah Miloudi, trainee coaching psychologist, working towards chartered status with the British Psychological Society
The boundary
I am not a financial adviser, and I will not become one by accident. I do not comment on products, allocations or numbers. What I do is sit with the client in the gap between the plan you have built and the life that it is supposed to afford them.
How this usually works
Firms bring me the problem rather than choosing from a list. You tell me what you are seeing across your client book, and I build the session around it.
Client webinars, with exercises.
One firm came to me because they kept having the same conversation: clients asking to draw down what they needed for an around the world trip, then not booking anything, because spending the money was frightening and nobody had thought about the life part of retirement at all. That became a session on retiring well. Another came with three things their clients got stuck on, communicating legacy plans, the psychology behind trust structures, and giving while alive. That became the session on the psychology behind inheritance tax. Both ended with evidence-based exercises people could actually use.
Webinars can be for your clients only, or open, in collaboration. Webinars can also be run as teach-ins for financial professionals, designed to help you have better conversations with clients.
Ninety minutes, one to one, for every retiring client.
One firm now funds a session with each client approaching retirement, as a part of what they offer. Usually there is something holding the person back. Sometimes it's an unwillingness to spend what they've built, other times it is a need to find a new purpose. Sometimes it's as simple as having the space to think about what they want retirement to look like in real terms, and how to make that happen.
Why firms do this
It solves a real client problem. Investing with intention and spending are part of a good financial plan. A client who cannot decide what the money is for or use what they have built is stuck, and no amount of financial modelling moves them.
And it changes how clients see you. People are more willing to talk about money, matters relating to intergenerational wealth, career longevity, legacy and other financial turning points than they used to be. An adviser who can name the emotional part of a decision, the way a good GP asks the question nobody else asked, becomes the one they recommend.
Credentials, in brief
- Psychology.
- M.A (hons) Psychology, first class, University of Glasgow. MSc Research Methods in Psychology, University of Strathclyde. Working toward chartership as a coaching psychologist with the British Psychological Society, anticipated ~2028/09, supervised throughout, and bound by the BPS code of ethics.
- Finance.
- More than ten years in the City, latterly at BlackRock. LLM Financial Regulation and Compliance. Award-winning financial journalist. I can follow a conversation about retirement and investing without needing it explained.
- Memberships.
- British Psychological Society, including the Division of Coaching Psychology and full membership of the Cognitive Psychology Section. Association for Coaching.
Full detail on the About page.
If you would like to know whether this is worth a conversation, with a specific client in mind or more generally, I would like to hear from you.